
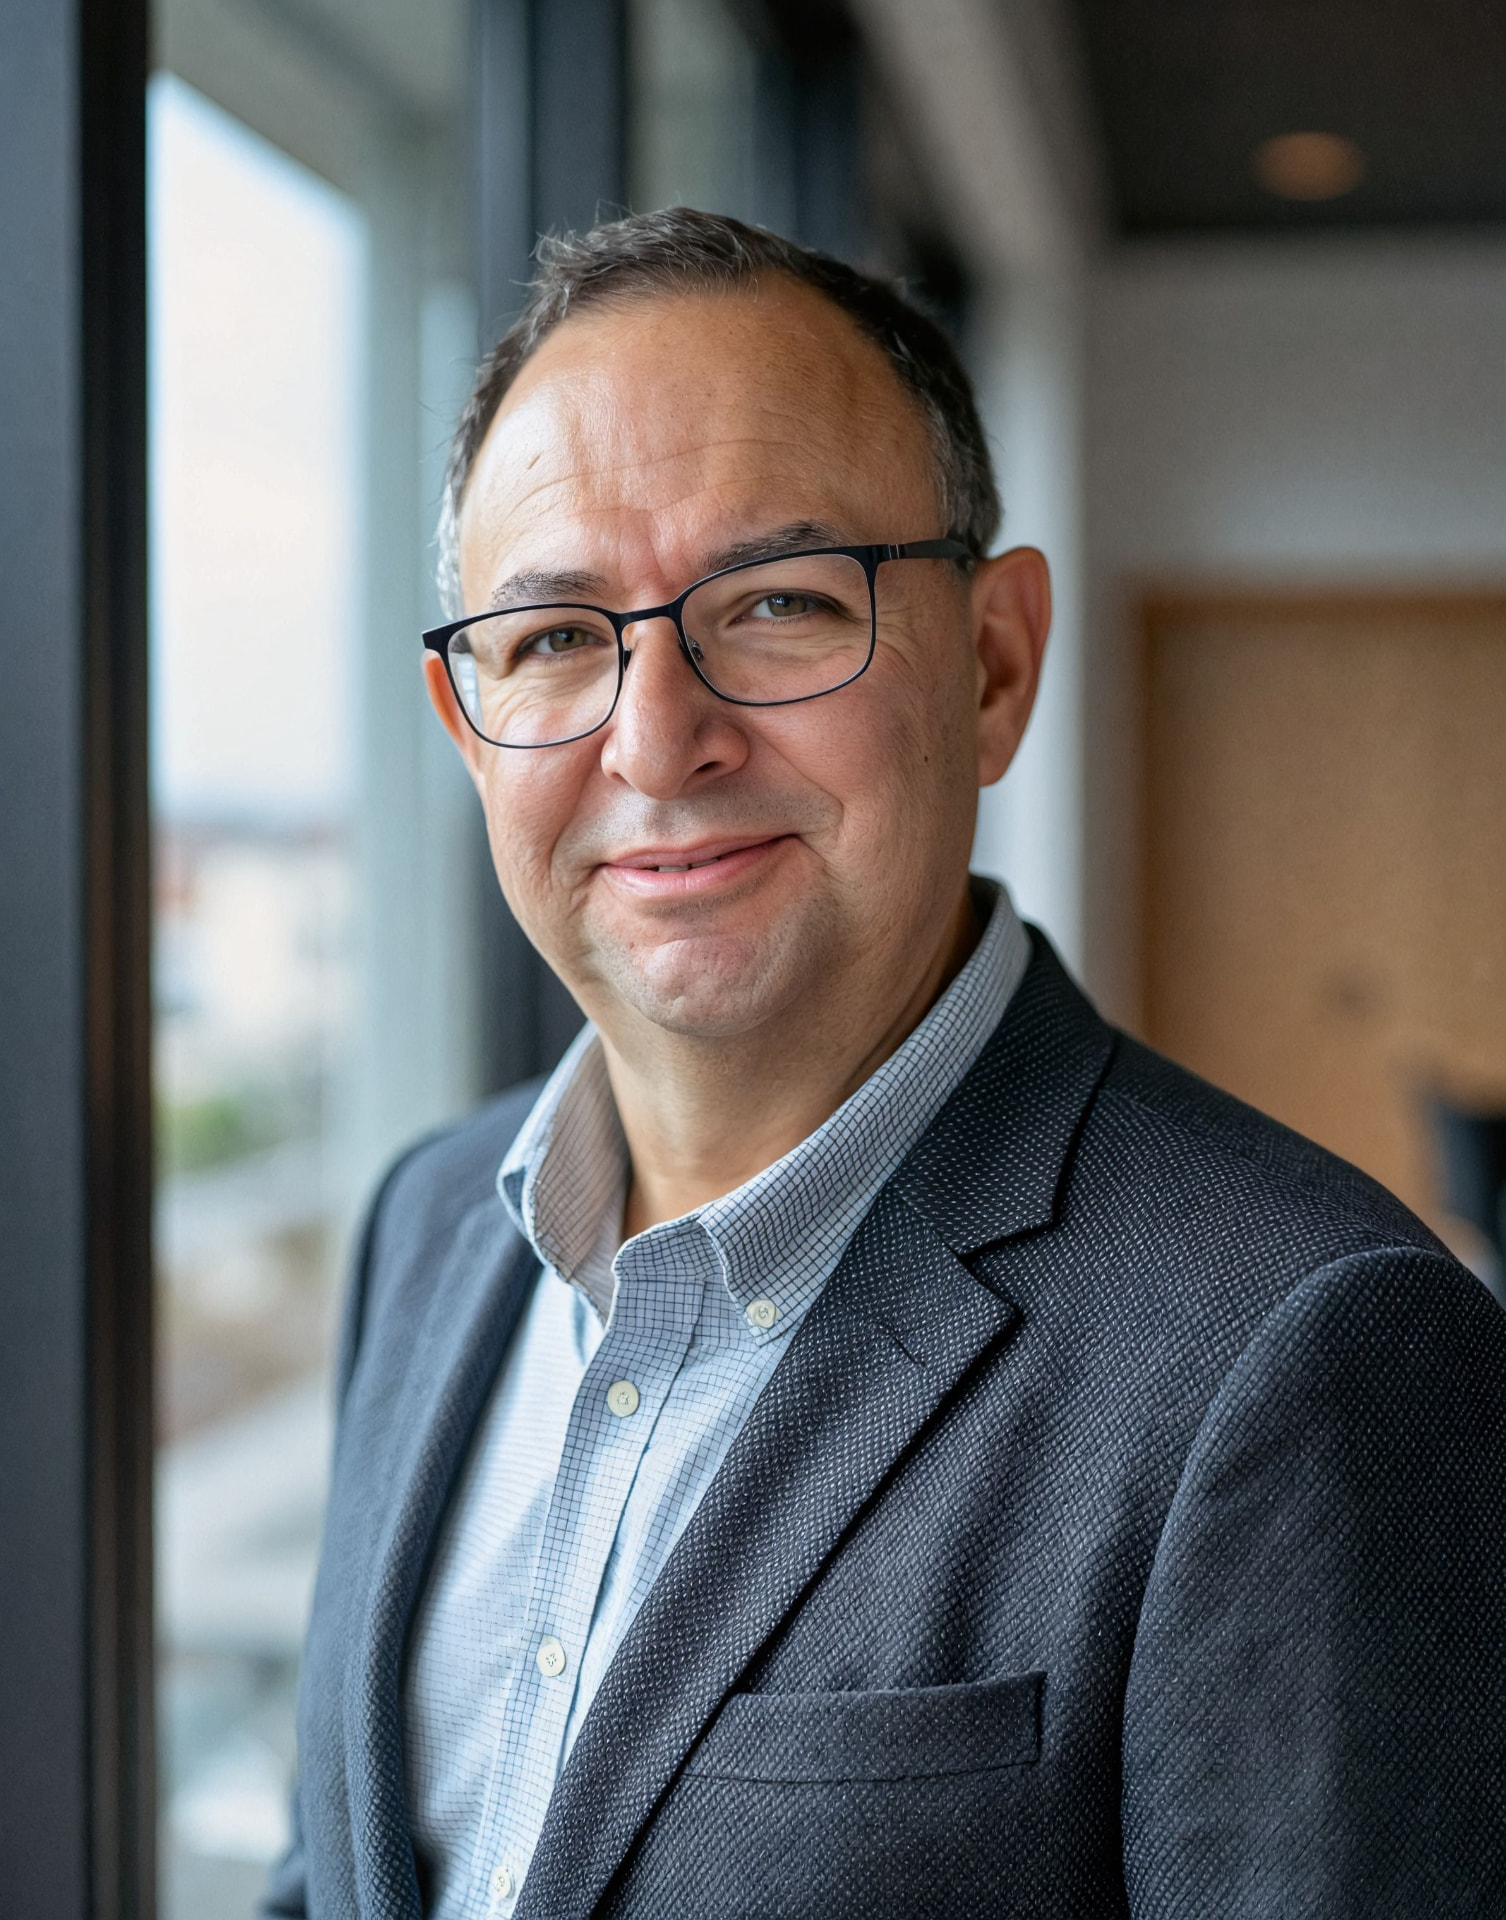
About Rich Arzaga, CFP®, CCIM
Rich Arzaga brings together two areas of expertise that are rarely found in one advisor: comprehensive financial planning and investment real estate.
As founder of The Real Estate Whisperer® Financial Planning, Rich provides comprehensive, flat-fee financial advice to households whose financial lives include directly owned investment real estate. His work brings real estate into the same conversation as retirement, investments, taxes, insurance, estate planning and the other decisions that shape a family's financial life.
Rich is both a CERTIFIED FINANCIAL PLANNER® professional and a Certified Commercial Investment Member (CCIM) and has taught personal financial planning at UC Berkeley for more than 20 years. He is also a frequent educator and speaker on the intersection of financial planning and real estate.
That combination of disciplines led Rich to develop The Real Estate Income Lab®, his process for moving from real estate data, to deeper property analysis, to financial-planning insight about what the real estate means for the family that owns it.
More About Rich
Rich's career has crossed financial planning, real estate, business and education.
Before founding The Real Estate Whisperer® Financial Planning, Rich founded and led Cornerstone Wealth Management from 2005 until its sale in 2021. Earlier in his career, he spent 18 years in senior-level business development roles across technology, publishing, travel, real estate and financial services. His last corporate role was as a vice president of a startup that was ultimately sold for $326 million.
That business background influences the way Rich approaches financial planning today. His CFP® and CCIM credentials bring together comprehensive financial planning and the analytical disciplines of investment real estate.
Over years of working directly with real estate owners, Rich saw a recurring problem: important real estate decisions were often being made separately from the rest of the financial plan. Property owners might know what they paid, what the property was worth and how much rent they collected, but those numbers alone didn't necessarily show what the property was actually contributing to their financial life.
That experience became the foundation for The Real Estate Income Lab®.
The process combines three disciplines: real estate conversation and coaching, deeper property-level financial analysis, and integration into the financial plan. Rich works with clients to understand the property and the investor's objectives; analyzes cash flow, expenses, NOI, cap rate, equity, debt, return and other relevant measures; and then brings those findings into the financial plan.
From there, the question becomes bigger than "Is this a good property?" The question is "What is this property doing for this family, and what could happen if they did something differently?"
Where appropriate, alternatives can then be modeled to compare keeping, improving, refinancing, selling, exchanging or repositioning the equity and to understand the potential effects on cash flow, taxes, retirement, risk and the broader financial plan.
Rich's real estate work also includes buy-sell-hold decisions, 1031 exchanges, tax strategies, inherited properties and determining how real estate fits within a client's broader financial life.
Education has also been an important part of Rich's career. He has taught in UC Berkeley's Personal Financial Planning program since 2006, where he has been recognized for teaching excellence, and has also taught through UC Santa Cruz Extension. He regularly speaks to financial planning, real estate and other professional audiences.
Rich and his wife met as undergraduates and have been married for more than 35 years. They raised two daughters, and family remains an important part of the life all this financial planning is ultimately supposed to support.
He's also a lifelong baseball fan who has visited all 30 Major League Baseball parks, which he maintains is a perfectly reasonable alternative to working out extensively.
Credentials, Education & Professional Background
Professional Credentials
- CERTIFIED FINANCIAL PLANNER® professional (CFP®)
- Certified Commercial Investment Member (CCIM)
- Colorado Licensed Real Estate Broker
- Certified Divorce Financial Analyst® (CDFA®)
- Certified in Long-Term Care (CLTC)
- Life & Health Insurance Licensed, including life, long-term care and disability insurance
The combination of the CFP® and CCIM credentials is particularly relevant to Rich's work because it brings comprehensive financial planning together with the financial analysis of investment real estate.
Education
- Personal Financial Planning Program, UC Berkeley
- Graduate Studies in Management, Northwestern University Kellogg School of Management
- Bachelor of Arts, San Jose State University
Teaching & Financial Education
Rich has served as an instructor and adjunct professor in UC Berkeley's Personal Financial Planning program since 2006. He is an honored instructor. Rich has also taught through UC Santa Cruz Extension, Silicon Valley.
His teaching and professional education work draws on both financial planning and real estate, with an emphasis on helping professionals understand how directly held investment real estate interacts with a client's broader financial life.
Selected Speaking Engagements
Rich has spoken to financial planning, real estate, investment and business audiences at national and regional conferences and professional programs. Selected engagements include:
- Financial Planning Association Annual Conference, Las Vegas, 2025
- C5 + CCIM Global Summit, 2025
- Financial Planning Association Retreat, 2025
- FPA NorCal Conference, 2025 and 2008
- Financial Planning Association of Southern Colorado, 2024
- National Association of REALTORS®, multiple programs
- Private Wealth Forum, Orlando, Seattle and San Francisco
- Commonwealth Club of San Francisco, 2007 and 2008
- National Tooling & Machining Association
- Financial Planning Association regional chapters, East Bay, San Francisco and Silicon Valley
- FPA Far West Roundup
- National Underwriter's Mastery Conference
Selected Honors & Recognition
- Journal of Accountancy Lawler Award, 2011, Best Article of the Year
- Charles L. Herrington Distinguished Service Award, 2010
- Associated Securities Distinguished Advisor Award, 2009, recognizing leadership contributions to the financial services industry
- Tim Koches Award for Teaching Excellence, 2008, UC Berkeley Personal Financial Planning Program
- Named by Worth Magazine among the Top 250 Wealth Advisors in the Nation, 2008-2009
Selected Media
The Wall Street Journal
BusinessWeek
Investor's Business Daily
Fox Business
Kiplinger
Kiplinger Retirement Newsletter
The Christian Science Monitor
Journal of Accountancy
Journal of Financial Planning
Journal of Financial Services
Chicago Tribune
San Francisco Chronicle
Contra Costa Times
San Jose Mercury News
Dallas-Fort Worth Star-Telegram
InvestmentNews
Financial Advisor Magazine
Financial Planning Magazine
Registered Rep. Magazine
REALTOR® Magazine
Real Estate Business
Selected Published Articles
Business & Professional Background
Before founding The Real Estate Whisperer® Financial Planning, Rich founded and served as CEO of Cornerstone Wealth Management, which he led from 2005 until its sale in 2021.
Before entering financial planning, Rich spent approximately 18 years in senior-level business development positions across publishing, technology, travel, real estate and financial services.
His final corporate position was as a vice president of a startup that was subsequently sold for $326 million.
That experience gives Rich firsthand familiarity with many of the decisions faced by professionals, executives, entrepreneurs and business owners, not simply from the perspective of a financial planner, but from having spent much of his career in business himself.
Professional Affiliations
- Financial Planning Association
- CCIM
- National Association of Residential Property Managers (NARPM®)
Why I Do This Work This Way
A personal standard
More than 20 years ago, while looking for my own financial advisor, I interviewed ten advisors using a checklist of the qualities and fiduciary standards I believed an advisor should meet.
That experience led to a simple decision: I wanted to become the kind of financial planner I had been looking for.
That principle still guides my work today. Your interests come first.
My Goal as Your Financial Planner
The objective
Your financial life is interconnected. Your income, investments, real estate, taxes, retirement, insurance, estate plan, debt, family, and the way you want to live, all affect one another.
My goal is to bring those pieces together and help you make thoughtful financial decisions.
Over more than 20 years of doing this work, I've seen how consequential a handful of better decisions can be. Decisions involving taxes, retirement, investments, real estate, insurance, Social Security or cash flow can potentially change a family's long-term financial picture by hundreds of thousands, and sometimes millions, of dollars.
But building the largest possible number isn't the goal.
The goal is what your money allows you to do: travel, spend with confidence, help your family, retire comfortably, give more, simplify your life, take less unnecessary risk and have greater freedom to live the way you want.
Your investments, your real estate and your financial plan are not the destination. Your life is.
What Guides My Work
Principles
Your whole financial life matters.
Financial decisions shouldn't be made in isolation. A decision involving a rental property can change your taxes, retirement income, cash flow, risk and estate plan. An investment decision can change what makes sense with your real estate.
The objective is to understand how the pieces work together and whether they support what you want your money to accomplish.
The advice should be about you.
I don't manage your investments or have financial products to sell. The starting point is your circumstances, resources, goals, preferences and priorities, not a product or an investment account.
Real estate belongs in the financial conversation.
When real estate represents a meaningful part of your wealth, it shouldn't sit outside the financial plan. We can consider its cash flow, equity, debt, taxes, return, risk, management demands and alternatives alongside everything else you own.
And that analysis needs to go deeper than property value and gross rent.
Over years of analyzing client-owned real estate, I've repeatedly found differences between the performance owners believe they're receiving and what a deeper review of the numbers shows. I call this The 5% Real Estate Performance Gap®, the potential spread between perceived and actual performance created by optimistic assumptions, untracked or irregular costs, and the absence of consistent performance measurement.
In my client work, I've often found that difference to be 5 percentage points or more. The percentage may sound small. The long-term financial consequence may not be, particularly when substantial equity and decades of ownership are involved.
Understanding that difference is one of the reasons I believe real estate analysis belongs inside comprehensive financial planning rather than beside it.
Better decisions can have enormous consequences.
Not every recommendation will be life-changing. But seemingly small changes can compound into substantial differences over time. Those opportunities are worth looking for.
The purpose of wealth is the life it makes possible.
Good financial advice isn't about maximizing net worth simply for the sake of having a bigger number. It should help create greater confidence, flexibility, choices and freedom to use what you've built in the ways that matter to you.
What You Can Expect From Me
Working together
Personal attention.
I intentionally maintain a boutique practice and work with a limited number of planning clients at a time. That allows me to give you and your financial questions the time, attention and thoughtful analysis they deserve.
I'll start by understanding you.
Our first conversations are about more than collecting financial data. I want to understand the help you're seeking, the questions you want answered, what matters most to you and what you want your resources to make possible.
I'll also look for risks, opportunities and connections you may not have recognized yourself.
I'll do the work necessary to reach a thoughtful answer.
I'll question assumptions, evaluate alternatives and dig into the details when they matter. When investment real estate is involved, that may mean going beneath the numbers initially provided to understand the property's actual cash flow and performance, then bringing that analysis into the financial plan through The Real Estate Income Lab®.
And if I don't know an answer, I'll tell you. I'll research it, consult appropriate resources when necessary and come back with a thoughtful response rather than pretend to know something I don't.
You'll understand the "why."
You shouldn't simply receive a list of recommendations.
I want you to understand what I recommend, why I recommend it, what alternatives we considered, and how the decision may affect the rest of your financial life.
If something requires more explanation, we'll spend more time on it.
You'll know what to do next.
A financial plan should lead to action.
You'll receive an executive summary and prioritized recommendations identifying important decisions, next steps and, when appropriate, the professionals needed to help implement them.
I can work with the professionals you already trust.
Good advice sometimes crosses professional boundaries.
With your authorization, I can coordinate as appropriate with your tax professional, attorney, investment advisor, insurance professional, real estate professional, trustee and other specialists so that decisions aren't being made without consideration of the broader financial picture.
I'll protect your information and respect your time.
Your personal and financial information will be kept confidential and safeguarded using appropriate security practices and technology.
I also believe responsiveness matters. I strive to return phone calls within one business day and emails within two business days, and to schedule our meetings with enough continuity to keep the work moving forward.
I'll act as a fiduciary.
This isn't simply a regulatory standard to me. It's the principle that led me into financial planning in the first place:
Your interests come first.
What I Ask of You
Your part
Good financial planning is collaborative. I'll bring the analysis, experience, curiosity and effort. I ask you to be an active participant in creating and implementing your plan.
Be open and candid.
Help me understand your complete financial picture, goals, concerns and priorities. The better I understand what matters to you, the better the advice I can provide.
Provide complete and timely information.
Good analysis depends on good information. I'll need you to provide requested documents and information as accurately and promptly as reasonably possible.
Help us maintain momentum.
Respond to reasonable requests, emails and questions so that we can keep the work moving forward.
Ask questions, and challenge my recommendations.
If something isn't clear, you disagree or you want to explore another alternative, tell me. You should understand and be comfortable with the decisions you ultimately make.
Be willing to challenge your own assumptions, too.
Good planning may confirm what you're already doing, or reveal a better alternative. Be willing to consider the evidence before deciding.
Keep me informed.
If something important changes in your financial life, family, goals or circumstances while we're working together, let me know.
Be prepared to act.
I'll help you understand your choices and make recommendations. The decisions are ultimately yours, and financial advice creates its greatest value when good decisions are put into action.
Does This Sound Like the Kind of Advice You're Looking For?
A simple first step
You don't need to have everything figured out before we talk. And you don't need to gather financial statements or documents for our initial conversation. Just bring what's on your mind.